

No longer a niche retirement tool
by Kate Beattie
Ms. Beattie is senior vice president, Retirement Income Strategy, with Capital Group.Please visit www.capitalgroup.com.As markets grow more complex, registered index-linked annuities (RILAs) have emerged as a powerful tool for retirement portfolios. Once viewed primarily as tactical strategies to protect an equity, multi-asset, or fixed income position, financial professionals now see them as strategic components of diversified portfolios, valued for their downside protection, allocation flexibility and ability to combine equity participation with guardrails.
At the same time, financial professionals continue to cite a need for clearer guidance, simpler materials and stronger education to help position these solutions confidently with clients.
Capital Group’s latest RILA Seller’s report* reveals a clear shift: RILAs are no longer viewed as niche tools, but as strategic solutions aligned to multiple client objectives.
How Are Financial Professionals Positioning RILAs Today?
Financial professionals are using RILAs to meet diverse client needs, from conservative investors seeking downside protection to growth-oriented investors looking for market participation with guardrails. Yet, when it comes to portfolio positioning, opinions diverge.
Some financial professionals present RILAs as a fixed income option, citing their potential to offer more upside with protection. “I sell it as a bond alternative,” one professional shared with researchers.
Others see them as an equity investment, particularly when tied to familiar benchmarks like the S&P 500 Index or Nasdaq-100 Index. “I see it as an equity sleeve,” another explained.
This dual perspective highlights the versatility of RILAs, but our research also showed that RILA use doesn’t stop there: As one financial professional put it, “Personally, I love them. I think they’ve gained a lot of popularity in the recent years, and I think it’s a great option for someone who is looking to participate in the market with a level of protection and a level of comfort.”
Other advantages financial professionals cited include:
- Risk management: Downside protection for pre-retirees and clients with lower risk tolerance.
- Tax deferral: For clients seeking tax-deferred growth outside of retirement accounts. “I think the low-cost tax deferral for some of the younger clients makes a lot of sense,” one RILA seller noted.
- Diversification: Blend of passive and active strategies to reduce market inefficiencies and broaden results.
“I think it’s a good product that solves a specific need for a client. It’s got almost the best of both worlds, if you will. It’s got some downside protection and upside growth as opposed to one or the other.” –Survey respondent
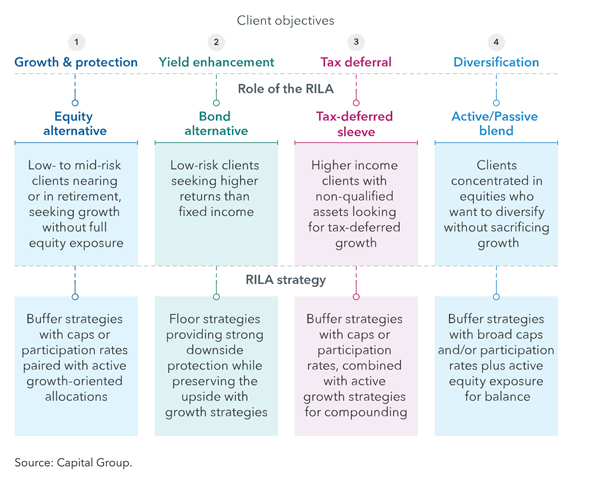
Clients value RILAs for a mix of features – downside protection, buffer/floor designs, income potential and the ability to be a growth investor with guardrails. Financial professionals tell us that these client priorities often map directly onto RILA strategies, reinforcing their role as more than just tactical buffers.
Whether positioned as equity alternatives, bond replacements, tax-deferred sleeves or diversification tools, RILAs give financial professionals a flexible way to help meet various client goals.
Active Strategies: A New Frontier In RILAs
In 2024, Capital Group began partnering with insurance carriers to bring active management into the RILA space, linking strategies to actively managed mutual funds and ETFs. This gave investors, for the first time, access to active flexibility within a traditionally passive structure, with the potential to achieve outcomes beyond traditional index-linked returns.
Although many financial professionals were initially unfamiliar with active RILA strategies, once introduced they expressed strong interest. They see active strategies as tools to adapt quickly to market shifts, capture opportunities and enhance diversification, especially in volatile environments where static index strategies may fall short. As one financial professional put it, “They will be able to react a little quicker to market changes.”
Financial professionals emphasized that execution matters: These strategies must be offered by credible managers, add no unnecessary complexity or cost and clearly align with client goals. When those conditions are met, they view active RILAs as a win-win that can help clients pursue growth with protection, while enabling financial professionals to build more resilient, differentiated portfolios.
*The RILA Seller’s report is based on in-depth conversations with 12 financial professionals across a wide range of client profiles, conducted in March and April 2025.


